Insurance agent resume examples & writing guide for 2026

Three insurance agent resumes at licensed agent, commercial producer and sales-manager level, rendered in a real template and annotated note by note. Every one names the license, the lines of business and the commission the agent actually wrote.

By the Resumi editorial teamUpdated 8 min read

Showing the mid-level example

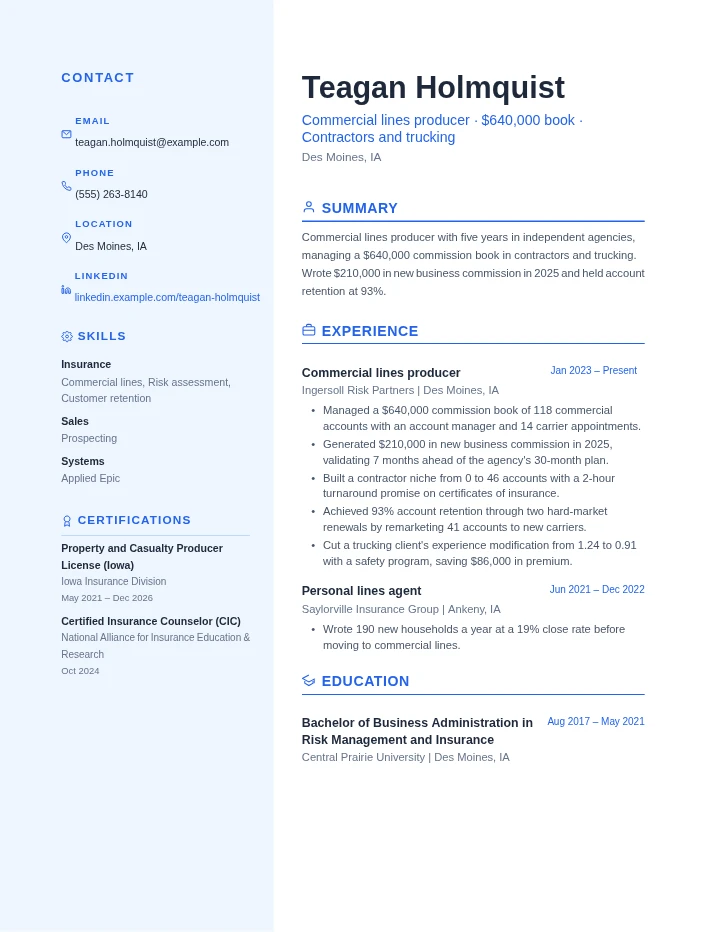
Insurance agent resume example, mid level, rendered in the Blue Professional template
Strength: Strong

Written by the Resumi editorial team for a fictional candidate. Role facts come from O*NET and the U.S. Bureau of Labor Statistics.

Strength band is Resumi’s optimization score, not a ranking any employer sees.

What makes this resume work

Each marker on the page has a note here. Press a marker to jump to its note.

  1. 1

    Book size and niche up top

    A $640,000 commission book in contractors and trucking. Agency owners hire producers by book size and niche, and this headline puts both in front of them before the summary starts.

  2. 2

    Commission, not premium

    New business commission of $210,000. Agencies pay producers on commission, not premium, so this is the figure an owner uses to judge whether a producer has paid for their salary.

  3. 3

    Validated ahead of plan

    Seven months ahead of a 30-month validation plan. New producers usually take two years or more to cover their cost, so finishing early is the strongest proof a mid-level producer can offer.

  4. 4

    Retention through a hard market

    Ninety-three percent retention while 41 accounts were moved to new carriers. Rising premiums push clients to shop, and keeping them takes remarketing work an owner can see in this bullet.

  5. 5

    Personal lines years as one line

    One hundred and ninety households a year in personal lines. The line explains the path into commercial work and gives a close rate, without spending space the commercial book needs.

Build your insurance agent resume

Free to start · no card

01The example, in full

The resume shown above, as text you can search and copy.

Teagan Holmquist

Commercial lines producer · $640,000 book · Contractors and trucking

Des Moines, IAteagan.holmquist@example.com(555) 263-8140linkedin.example.com/teagan-holmquist

Summary

Commercial lines producer with five years in independent agencies, managing a $640,000 commission book in contractors and trucking. Wrote $210,000 in new business commission in 2025 and held account retention at 93%.

Experience

Commercial lines producer

Jan 2023 – Present

Ingersoll Risk Partners · Des Moines, IA

  • Managed a $640,000 commission book of 118 commercial accounts with an account manager and 14 carrier appointments.
  • Generated $210,000 in new business commission in 2025, validating 7 months ahead of the agency's 30-month plan.
  • Built a contractor niche from 0 to 46 accounts with a 2-hour turnaround promise on certificates of insurance.
  • Achieved 93% account retention through two hard-market renewals by remarketing 41 accounts to new carriers.
  • Cut a trucking client's experience modification from 1.24 to 0.91 with a safety program, saving $86,000 in premium.

Personal lines agent

Jun 2021 – Dec 2022

Saylorville Insurance Group · Ankeny, IA

  • Wrote 190 new households a year at a 19% close rate before moving to commercial lines.

Education

Bachelor of Business Administration in Risk Management and Insurance

Aug 2017 – May 2021

Central Prairie University · Des Moines, IA

Skills

Insurance
Commercial lines, Risk assessment, Customer retention
Sales
Prospecting
Systems
Applied Epic

Certifications

Property and Casualty Producer License (Iowa)

May 2021

Iowa Insurance Division

Certified Insurance Counselor (CIC)

Oct 2024

National Alliance for Insurance Education & Research

02Market snapshot

Median pay
$62,280 median annual pay, and $73,440 at health and medical insurance carriers
Typical education
High school diploma typical, plus courses and a state exam for each license
Job outlook
3% growth from 2025 to 2035, as fast as average, about 43,100 openings a year
Common credentials
State license required, separate for property and casualty and for life and health, with continuing education

Sources: BLS OES (May 2025) · BLS OOH (2025)

03The same resume at three levels

The tinted row is the level shown above.

  • Entry-level

    0–2 years

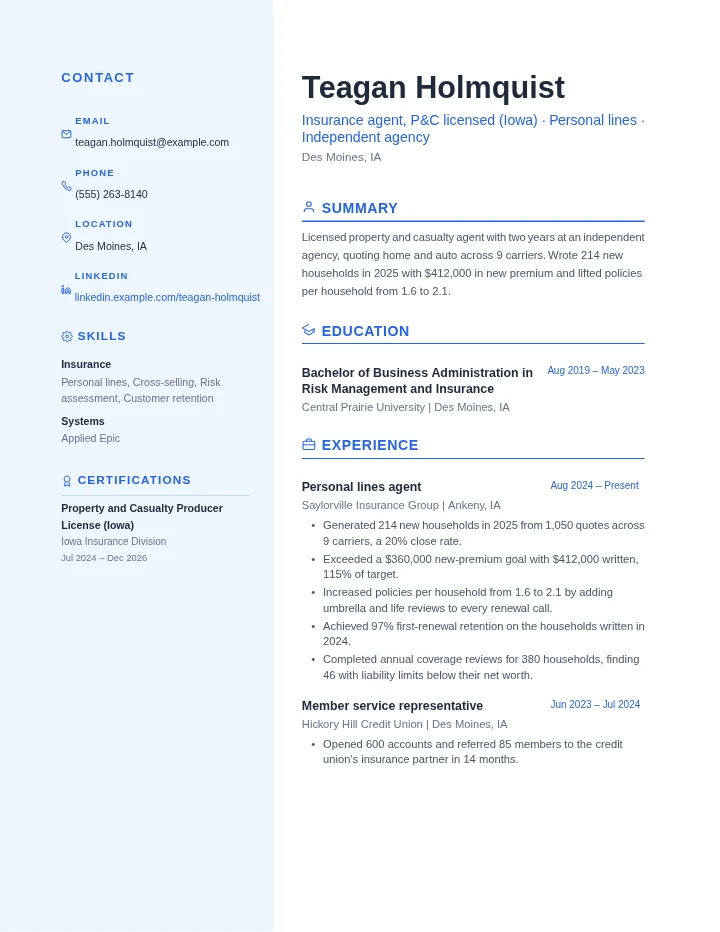
    Education sits above the jobs, and the headline names the license, the state and the lines. Bullets count households and premium, quotes and close rate, policies per household, first-renewal retention and coverage reviews. The license sits in certifications with its renewal date.

    Typical titles: Personal lines agent, Licensed insurance agent, Inside sales producer

  • Mid-level

    3–6 years

    Ownership moves to the front: the commission book, the accounts and the carriers, then new business commission and validation against plan. A niche built from zero, retention in a hard market and a client's experience modification each get a bullet. The CIC joins the license.

    Typical titles: Commercial lines producer, Insurance producer, Commercial account executive

  • Senior

    7+ years

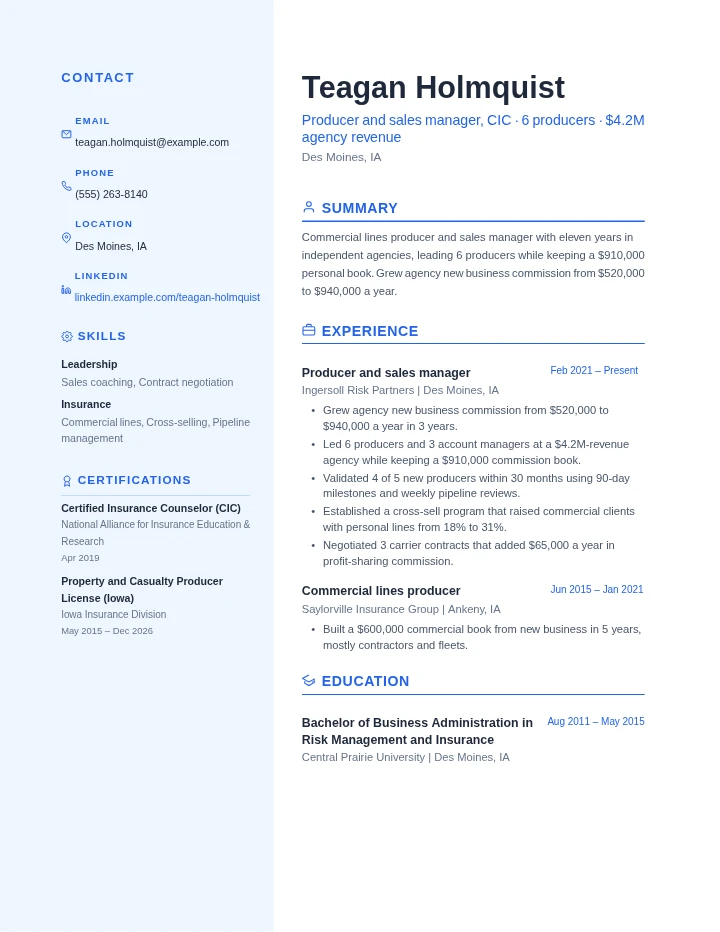
    Scope replaces individual production: agency new business growth, a team of producers and account managers, a personal book kept, validation record, carrier contracts and a cross-sell program. The earlier producer years fold to one line with the book built from new business.

    Typical titles: Producer and sales manager, Agency principal, Senior commercial producer

04Summary

Weak

Dedicated and personable insurance professional with a passion for helping clients protect what matters most and a track record of exceeding sales goals.

Strong

Commercial lines producer with five years in independent agencies, managing a $640,000 commission book in contractors and trucking. Wrote $210,000 in new business commission in 2025 and held account retention at 93%.

The agency type, the book in commission, the niche, new business and retention. An agency owner can judge whether this producer pays for their seat in one read. The weak version promises to protect what matters without a license, a line of business or a number.

05Bullets

Weak

  • Sold insurance policies to new and existing clients and provided excellent customer service to maintain strong relationships.

Strong

  • Achieved 93% account retention through two hard-market renewals by remarketing 41 accounts to new carriers.

A retention rate, the market conditions behind it and the work that held it. An owner knows how hard rising premiums make renewals, and can ask which carriers took the 41 accounts. The weak bullet names no line of business, no book size and no result, so it could sit on any sales resume in any industry without a change.

06Skills and keywords

Insurance

  • Commercial lines (in the example)
  • Personal lines (in the example)
  • Risk assessment (in the example)
  • Customer retention (in the example)
  • Cross-selling

Sales

  • Prospecting (in the example)
  • Pipeline management
  • Contract negotiation

Systems

  • Applied Epic (in the example)
  • Salesforce
  • Excel

Licenses and designations

  • Property and casualty license (in the example)
  • Life and health license
  • Certified Insurance Counselor (CIC) (in the example)
  • FINRA Series 6

Filled chips appear in the example above.

Paste a job description and Resumi shows which of these your resume already covers.

Build your insurance agent resume

07Mistakes to avoid

  1. License buried at the bottom or missing

    Fix: Agencies cannot let you quote or bind without the right license in the right state. Put the license type and state in your headline or first line, and keep the full license, with its renewal date, in a certifications section.

  2. Premium reported when the agency counts commission

    Fix: Producers are paid and judged on commission. Give your book and your new business in commission dollars, and add premium only as context. An owner who sees only premium has to guess what you actually earned the agency.

  3. No line of business or niche named

    Fix: Personal lines, small commercial and specialty niches such as contractors or trucking are different jobs. Name your lines and any niche in the headline, so the owner can see whether you fit their book and their carriers.

  4. Retention left out entirely

    Fix: A producer who writes new business but loses renewals leaves the agency no better off. Give your account or policy retention, especially through rate increases, and the remarketing or reviews that kept clients.

  5. Policies sold with no close rate or household count

    Fix: Policies sold can be inflated by small add-ons. In personal lines, give new households, quotes and close rate, and policies per household. Those are the ratios agency owners use to compare agents.

08Format and template

Reverse-chronological order, standard section headings, and every figure written as text. Put the license, the state and your lines of business near the top. Keep licenses and designations in a certifications section with dates, because licenses renew and continuing education is required. Name your lines of business in the headline too. This example uses Blue Professional. The same content works in Standard, Executive Classic and Beige Two-Column.

Shown above: Blue Professional

  • Standard template
    StandardFree
  • Executive Classic template
    Executive Classic
  • Beige Two-Column template
    Beige Two-Column

09Questions insurance agents ask

Where should I put my insurance license on my resume?

In two places. Name the license type and state in your headline or first line, such as P&C licensed in Iowa, so it is the first thing an agency sees. Then list the full license in a certifications section with the issuing state and renewal date. If you hold licenses in more than one state, list each. Many agencies also ask for your national producer number on the application, so keep it handy.

What numbers should an insurance agent put on a resume?

In personal lines: new households, quotes and close rate, written premium, policies per household and retention. In commercial lines: commission book size, new business commission, account count, retention and average account size. Give each one a period and, where you can, a goal you beat. Agency owners compare producers on these ratios, so a resume that uses them speaks their language.

Is the CIC or CPCU worth it for an insurance agent?

Designations help once you have the license and some production. The Certified Insurance Counselor from the National Alliance takes five courses with exams and requires an annual update. Many agencies sponsor designations for producers they want to keep. They signal technical depth to clients and carriers, but agency owners still hire mostly on book, new business and retention, so list designations in certifications.

How do I write an insurance resume if I have not validated yet?

Show the pace. Give new business commission for each quarter or year so far, your pipeline, the niche you are building and the account count. Validation often takes two years or more for new producers, so an owner will judge the trend rather than the total. A bullet showing steady growth toward the agency's plan reads better than leaving the topic out.

How do I move from customer service into an insurance sales role?

Get licensed first, then show the selling you already do. Referrals you made, coverage reviews you ran, cross-sells you added on service calls and accounts you kept all count. Many agencies hire licensed service staff into inside sales seats. Put the new license in your headline and lead your current role with any number tied to sales, such as referrals or accounts kept.

Should I list the carriers I am appointed with?

Name the count and, if space allows, the types, such as 14 carrier appointments across standard and specialty markets. Owners want to know whether you can place hard risks. Listing every carrier by name takes space and can tie you to markets the new agency does not use. Mention a specific carrier only when it explains a result, such as moving accounts during a hard market.

Free to start

Build your insurance agent resume

No card, no trial that turns into a charge.

Sign up free