Loan officer resume examples & writing guide for 2026

Three loan officer resumes at new, producing and branch manager level, rendered in a real template and taken apart line by line. Each one carries the license status, the volume in dollars and units, and the purchase share.

By the Resumi editorial teamUpdated 10 min read

Showing the mid-level example

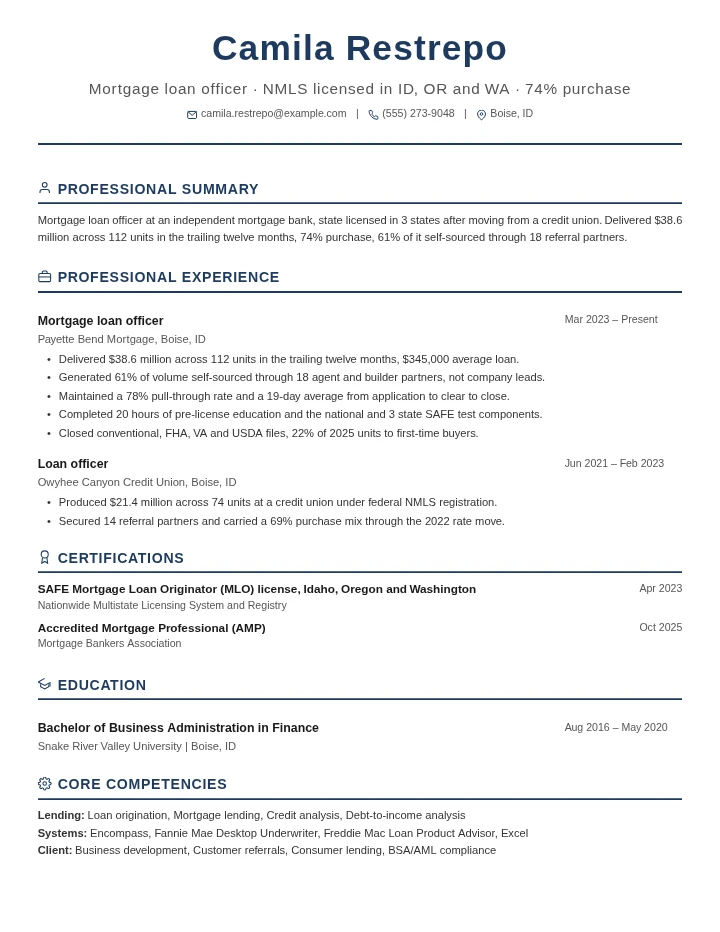
Loan officer resume example, mid level, rendered in the Executive Classic template
Strength: Excellent

Written by the Resumi editorial team for a fictional candidate. Role facts come from O*NET and the U.S. Bureau of Labor Statistics.

Strength band is Resumi’s optimization score, not a ranking any employer sees.

What makes this resume work

Each marker on the page has a note here. Press a marker to jump to its note.

  1. 1

    Licensed, and in which states

    State licensed in three states, with the purchase share beside it. Multi-state licensure is an active hiring preference, and the states are the first thing a manager checks against the territory they are trying to cover.

  2. 2

    A dated window, not a total

    The trailing twelve months, $38.6 million, 112 units. Recruiters pull production from third-party data before they call and look back a year or more, so a career total that cannot be matched to a window invites doubt.

  3. 3

    Self-sourced share, with partners

    Sixty-one percent self-sourced through 18 agent and builder partners. Company leads and business you found yourself are paid differently under the federal compensation rule, which is exactly why a manager asks for the split.

  4. 4

    Two process numbers

    A 78% pull-through rate and 19 days from application to clear to close. Lenders are cutting cost per loan, so an originator who can show the file moves cleanly is arguing about their own cost, not just their volume.

  5. 5

    Product mix and buyer type

    Conventional, FHA, VA and USDA on one line, with 22% of units going to first-time buyers. Product range says which borrowers this originator can serve, and the first-time share says where the referral partners are sending people.

  6. 6

    Credit union years kept whole

    Volume, units and a 69% purchase mix held through a year when rates moved. The earlier seat is worth keeping because it shows the book survived a market turn, which is the question every hiring manager is really asking.

Build your loan officer resume

Free to start · no card

01The example, in full

The resume shown above, as text you can search and copy.

Camila Restrepo

Mortgage loan officer · NMLS licensed in ID, OR and WA · 74% purchase

Boise, IDcamila.restrepo@example.com(555) 273-9048

Summary

Mortgage loan officer at an independent mortgage bank, state licensed in 3 states after moving from a credit union. Delivered $38.6 million across 112 units in the trailing twelve months, 74% purchase, 61% of it self-sourced through 18 referral partners.

Experience

Mortgage loan officer

Mar 2023 – Present

Payette Bend Mortgage · Boise, ID

  • Delivered $38.6 million across 112 units in the trailing twelve months, $345,000 average loan.
  • Generated 61% of volume self-sourced through 18 agent and builder partners, not company leads.
  • Maintained a 78% pull-through rate and a 19-day average from application to clear to close.
  • Completed 20 hours of pre-license education and the national and 3 state SAFE test components.
  • Closed conventional, FHA, VA and USDA files, 22% of 2025 units to first-time buyers.

Loan officer

Jun 2021 – Feb 2023

Owyhee Canyon Credit Union · Boise, ID

  • Produced $21.4 million across 74 units at a credit union under federal NMLS registration.
  • Secured 14 referral partners and carried a 69% purchase mix through the 2022 rate move.

Education

Bachelor of Business Administration in Finance

Aug 2016 – May 2020

Snake River Valley University · Boise, ID

Skills

Lending
Loan origination, Mortgage lending, Credit analysis, Debt-to-income analysis
Systems
Encompass, Fannie Mae Desktop Underwriter, Freddie Mac Loan Product Advisor, Excel
Client
Business development, Customer referrals, Consumer lending, BSA/AML compliance

Certifications

SAFE Mortgage Loan Originator (MLO) license, Idaho, Oregon and Washington

Apr 2023

Nationwide Multistate Licensing System and Registry
Accredited Mortgage Professional (AMP)

Oct 2025

Mortgage Bankers Association

02Market snapshot

Median pay
$76,690 median annual pay, $36.87 an hour
Typical education
Bachelor's degree, usually business or finance. Less than 5 years of related experience and moderate-term on-the-job training
Job outlook
+1% employment change, 2025-35, slower than average. About 17,100 openings a year
Common credentials
Mortgage loan officers need a Mortgage Loan Originator license: prelicensing courses, a national exam, background and credit checks, renewed each year

Sources: BLS OES (May 2025) · BLS OOH (2025)

03The same resume at three levels

The tinted row is the level shown above.

  • Entry-level

    0–2 years

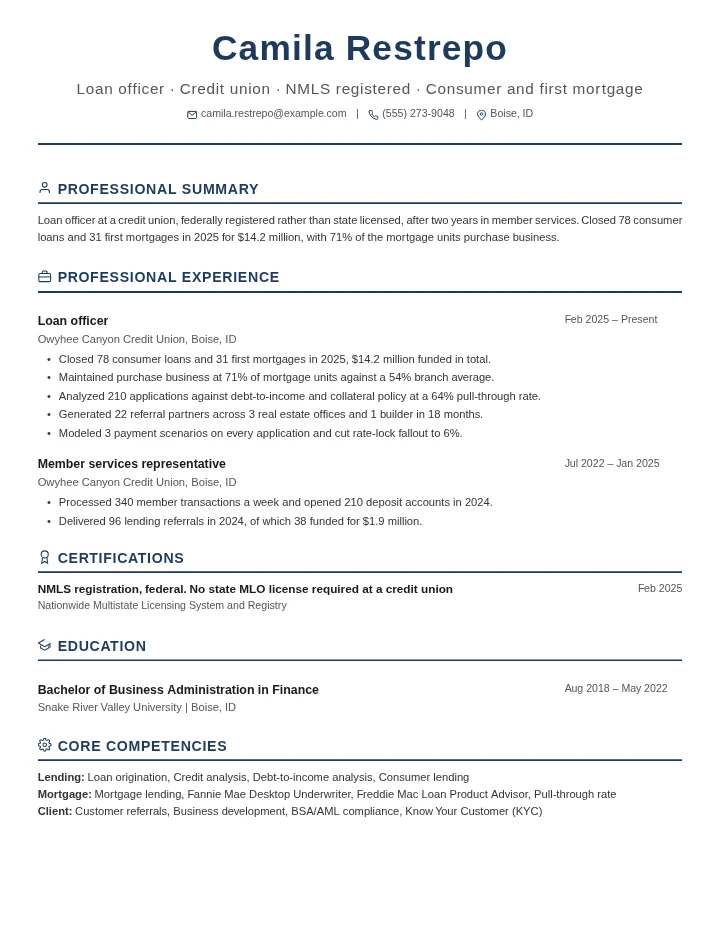
    Experience leads because the first year produced closings rather than coursework. The headline settles the registration question before the summary begins. Every bullet carries units, dollars or a rate, the member services years read as a referral pipeline rather than a teller job, and the pull-through rate sits among them.

    Typical titles: Loan officer, Consumer lender, Junior mortgage loan officer

  • Mid-level

    3–6 years

    The headline carries the license and the states. Each bullet gives a number a hiring manager can verify: the dated window, the self-sourced share, the pull-through rate and the cycle time. The credit union years stay because they show the same person producing under a different regime and through a rate move.

    Typical titles: Mortgage loan officer, Senior loan officer, Mortgage loan originator

  • Senior

    7+ years

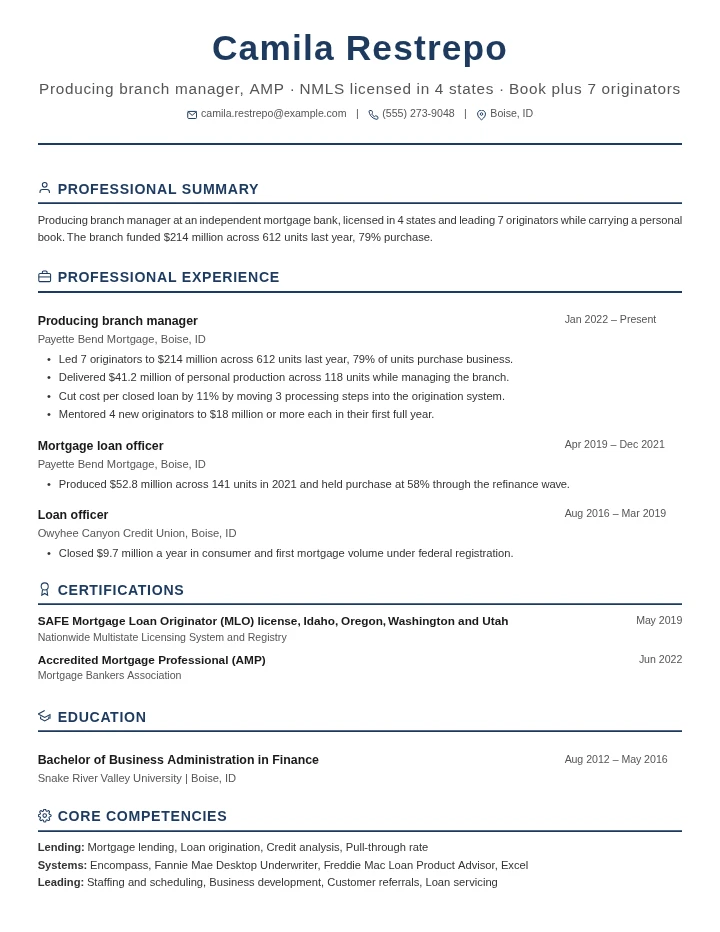
    Scope and production run side by side: originators led, branch volume in units and dollars, personal production kept separate, cost per loan taken down and four producers ramped past $18 million each. The peak refinance year keeps its purchase share so the number cannot be discounted, and the first seat holds one line.

    Typical titles: Producing branch manager, Sales manager, mortgage, Senior mortgage loan officer

04Summary

Weak

Results-driven mortgage professional with a proven track record of exceeding sales goals and delivering exceptional customer service to borrowers throughout the loan process.

Strong

Mortgage loan officer at an independent mortgage bank, state licensed in Idaho, Oregon and Washington. Delivered $38.6 million across 112 units in the trailing twelve months, 74% purchase, 61% of it self-sourced through 18 referral partners.

License status and states, a dated window, dollars and units together, the purchase share and the self-sourced share. A branch manager can check every one of those against production data they already pull. The weak version is what every applicant writes and it settles nothing.

05Bullets

Weak

  • Responsible for originating residential mortgage loans and building relationships with real estate agents and other referral sources.

Strong

  • Generated 61% of volume self-sourced through 18 agent and builder partners, not company leads.

Company leads and business you found yourself are paid differently under the federal compensation rule, which is exactly why a hiring manager wants the split. A share and a partner count are both checkable, and together they say whether the book might travel. The weak bullet describes the job rather than the person doing it, and every applicant for the role could have written it unchanged.

06Skills and keywords

Origination

  • Loan origination (in the example)
  • Mortgage lending (in the example)
  • Credit analysis (in the example)
  • Debt-to-income analysis (in the example)
  • Consumer lending (in the example)
  • Commercial lending
  • Loan servicing
  • Pull-through rate (in the example)

Systems

  • Encompass (in the example)
  • Fannie Mae Desktop Underwriter (in the example)
  • Freddie Mac Loan Product Advisor (in the example)
  • Excel (in the example)
  • Calyx Point
  • Salesforce

Clients and compliance

  • Business development (in the example)
  • Customer referrals (in the example)
  • BSA/AML compliance (in the example)
  • Know Your Customer (KYC)
  • Fraud detection

Credentials

  • SAFE Mortgage Loan Originator (MLO) (in the example)
  • Accredited Mortgage Professional (AMP) (in the example)
  • Certified Mortgage Banker (CMB)
  • Certified Commercial Loan Officer (CCLO)
  • Accredited Financial Counselor (AFC)

Filled chips appear in the example above.

Paste a job description and Resumi shows which of these your resume already covers.

Build your loan officer resume

07Mistakes to avoid

  1. Volume written with no units and no year

    Fix: A dollar total on its own cannot be checked or divided. Give the twelve months, the units behind the dollars, and the average loan they imply. Recruiters pull production from outside data before they call, so a figure that will not reconcile is worse than none.

  2. Licensed and registered used as the same word

    Fix: A state-licensed originator sat a national and a state test, did 20 hours of pre-license education and renews with 8 hours a year. One registered at a bank or credit union did none of that. Say which you are, and name the states.

  3. No purchase share anywhere on the page

    Fix: A book built on refinances and one built on purchases are different businesses, and the share is how a manager tells them apart. Write it as a percentage of units for a named year, next to the volume it belongs to.

  4. Self-sourced production left implicit

    Fix: Company leads and business you found yourself are paid differently, so the split is the first thing a manager asks about. Name the share you sourced and the partners behind it. A partner count is a metric in this field, not a soft skill.

  5. A commission split or basis points on the page

    Fix: Your comp plan is your former employer's number and belongs in the negotiation, not the resume. Put the production those basis points were paid on instead, and keep the lead-source split, which is the part that says something about you.

08Format and template

Single column, standard headings, no photo. A lending manager reads the license line, the trailing twelve months and the purchase share before anything else, so all three belong above the fold, and a two-column layout can push the license away from the name it belongs to. This example uses Executive Classic, which gives the license and the designation a dated row of their own. The same content works in Standard, Warm Classic and Maroon Elegant, all single column.

Shown above: Executive Classic

  • Standard template
    StandardFree
  • Warm Classic template
    Warm Classic
  • Maroon Elegant template
    Maroon Elegant

09Questions loan officers ask

What is the difference between a licensed and a registered loan officer?

Where you work decides it. Originate residential mortgages for an independent lender or a broker and you are state licensed: 20 hours of pre-license education, a national test plus a state component for each state, fingerprints, a background and credit check, and 8 hours of continuing education every year. Do the same work for a bank or credit union and you are federally registered instead, with none of that. Both carry an identifier on the registry. Write which one you hold, because the manager reading it may have to sponsor the other.

What numbers belong on a loan officer resume?

Volume and units together for a named twelve months, the average loan they imply, the purchase share as a percentage of units, the share you sourced yourself, your referral partner count, pull-through rate and days from application to clear to close. Write the window, not a career total, because a career total cannot be matched against what a recruiter has already looked up. Leave your commission split and your basis points off the page entirely.

My strongest years were refinances and the market has turned. How do I write that?

Name the year and put the purchase share beside the volume, even when the share was low. A big number from a refinance wave with no year attached reads as a number that will not repeat, and the reader discounts the whole page. A big number labelled with its year and its mix reads as honest, and the purchase percentage you did hold becomes the evidence that you can work a purchase market. Then give the current twelve months underneath it.

How do I write a commercial, SBA or underwriting resume instead of a mortgage one?

Change the unit, because these are different jobs sharing one title. Commercial lending is measured by the client, not the loan: portfolio size, number of relationships, the revenue band of the companies you cover, deposits gathered and credit quality. Small business lending is measured by deal size and self-sourcing. Underwriting is measured by authority, product and pipeline rather than production. Mortgage licensing on a commercial resume signals the wrong track, so take it off.

I am coming from a branch or a processing seat with no production. What goes where volume should be?

The pipeline you fed and the files you moved. Referrals sent to the lending desk and how many funded, applications taken, documents cleared inside a stated turnaround, approval rates on files you prepared, and the systems you worked in. Then name what you have done about licensing, because a manager weighing an unlicensed hire is really weighing how long until you can take an application on your own.

How long should a loan officer resume be?

One page. Production is the point and it compresses well: a dated twelve months, the two previous years, and one line for each earlier seat. The branch manager example here holds ten years on a single sheet by keeping only the scope and one number for each earlier role. A second page is fair for a regional or divisional leader with several branches and a hiring record to account for.

Free to start

Build your loan officer resume

No card, no trial that turns into a charge.

Sign up free